Peirce Exit Leaves SEC With Two as CFTC Has One Commissioner
Hester Peirce’s October 2 exit will leave SEC CFTC commissioners at three combined as crypto policy moves ahead without the CLARITY Act.
Hester Peirce’s planned departure on Friday, October 2, will leave the SEC with two commissioners and the CFTC with one, giving the agencies three commissioners combined to oversee parts of a $3 trillion crypto industry. The reduced rosters come as the White House has yet to announce replacements and both regulators continue shaping policy without the CLARITY Act, leaving leadership capacity and rulemaking direction in focus.
SEC and CFTC leadership will shrink to three commissioners combined
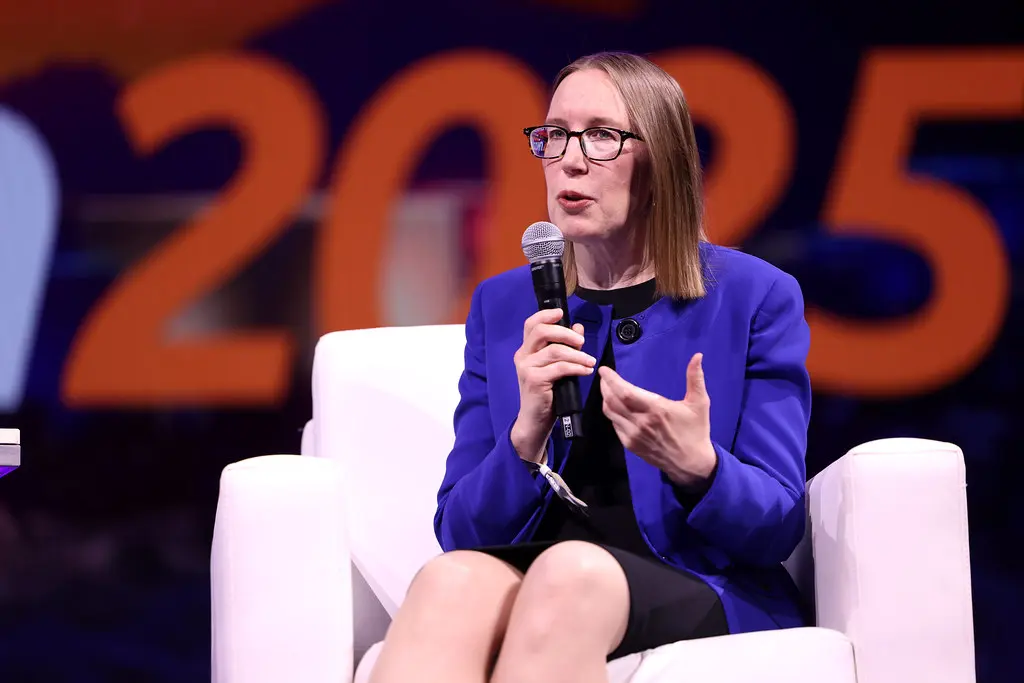
Peirce, a Republican member of the Securities and Exchange Commission, is set to leave after eight years at the agency, about two months before the end of the 18-month extension for her second term. Her departure would leave SEC Chair Paul Atkins and Commissioner Mark Uyeda as the agency’s only commissioners. Both are Republicans, on a panel generally expected to have five members.
The SEC has operated with only two commissioners just once before, according to the source report. That makes the expected change unusual in the agency’s history, although the immediate operational effect will depend on the decisions before the remaining commissioners and how the agency handles its ongoing work.
The Commodity Futures Trading Commission is already operating with a single commissioner. Chair Michael Selig has led the agency alone since December 2025, when acting chair Caroline Pham departed. The combined count of three therefore reflects two officials at the SEC and one at the CFTC, not three commissioners at each regulator.
Under federal law, President Donald Trump is the only official who can nominate replacements for vacant seats at both agencies. The White House had not announced nominees or a formal intention to nominate additional commissioners in the report, though a White House official indicated that the president intended to make nominations in the near future. Any nominees would still need Senate confirmation before taking office.
CNBC reported on September 4 that White House officials were vetting four candidates for open CFTC seats, without identifying them. That report points to possible candidate review, but it does not establish that nominees have been selected or that the vacancies will be filled on a particular timetable.
The staffing gap matters for crypto firms following the SEC’s interpretation of securities rules, including its staff guidance on crypto policy questions. Guidance can influence compliance decisions, but it is distinct from legislation and does not itself settle every question about how federal law applies to digital assets.
Crypto policy continues without the CLARITY Act
The SEC and CFTC oversee different aspects of a crypto market that the source report puts at $3 trillion. Their reduced leadership comes after the Digital Asset Clarity Act, commonly called the CLARITY Act, failed in the Republican-controlled Senate earlier in September. The bill was expected to give the CFTC more authority over digital-asset regulation in areas currently handled by the SEC.
Without the bill’s passage, the division of responsibilities remains a live policy issue rather than one newly settled by Congress. The agencies are continuing to apply existing federal laws through their own rulemaking and interpretations, so market participants must track both regulators’ actions instead of relying on a new congressional framework to clarify the boundary.
The distinction is material for token issuers and crypto businesses assessing which rules may apply to a product or activity. The SEC has issued staff guidance on investment contracts, while the CFTC has addressed how companies could use blockchain recordkeeping. Those steps show policy work is proceeding, but neither is equivalent to the broader statutory allocation of authority the CLARITY Act was expected to provide.
The Senate setback therefore leaves companies with an interim policy environment shaped by agency interpretation. The CFTC’s approach to digital-asset rules under existing authority is part of that process, as is the unsettled legislative question of how much oversight should shift from the SEC to the commodities regulator.
For crypto investors, the near-term significance is regulatory rather than a direct market-price signal: the leadership count alone does not establish that enforcement or rulemaking will stop. It does mean that policy direction is being set by a small number of officials while the legislative framework remains unresolved, making agency announcements and formal rulemaking important signals for firms and investors monitoring US exposure.
Vacancies leave rulemaking and appointments in focus
Both agencies continue to advance crypto oversight through rulemaking and interpretations of existing federal law. The CFTC said it welcomed new commissioners once they are nominated and confirmed, and maintained that it was equipped to oversee its part of the crypto market. That response indicates the agency does not consider its reduced roster a bar to continuing its work, but it does not resolve how vacancies could affect the pace or direction of future decisions.
The question is not only whether the agencies can continue issuing guidance, but how durable and broadly supported their policy choices will be while seats remain open. A fuller commission could bring additional perspectives to deliberations; until appointments are made, the current leadership will continue to manage rulemaking and oversight within the authority already available to each regulator.
Senate Democrats raised a related governance concern in a June letter to Trump and Senate Majority Leader John Thune, arguing that Congress designed agencies including the SEC and CFTC to be bipartisan. They criticized the administration’s handling of vacancies. That political dispute does not change the agencies’ current powers, but it underlines why nominations and confirmation proceedings may carry implications beyond simply restoring headcount.
The CFTC’s rulemaking timetable is another piece of the picture, particularly where executive review and stalled legislation affect the next steps. Existing-authority efforts remain relevant while lawmakers have not passed the CLARITY Act, but the available reporting does not establish a date for new rules or a timetable for Senate action on the bill.
The immediate milestones are therefore formal nominations, Senate confirmation, and any further congressional action on the CLARITY Act. The White House has signaled an intention to nominate members in the near future, but no formal nominees or candidate names were identified in the report. Until that changes, the SEC is set to operate with two commissioners after Peirce leaves on October 2, while Selig remains the CFTC’s sole commissioner.
Further movement on the bill could alter the SEC-CFTC division of crypto oversight; until then, the agencies’ actions under existing law will continue to shape the operating environment. Follow CoinNews on X and Telegram for ongoing crypto market and policy updates.