Korean Stock Tokenization Plans Face Regulatory Hurdles
Kakaopay’s Dinari and Ondo agreements explore tokenized Korean stocks, but custody, investor rights and regulation must be resolved first.
Kakaopay Securities has announced separate agreements with Dinari and Ondo Finance to explore putting Korean-listed stocks onchain and distributing them to international investors. The work is exploratory, not a commercial offering: any launch would depend on legal and regulatory requirements in South Korea and overseas markets.
Two agreements target different parts of a potential offering
Announced on Tuesday, September 29, 2026, the agreements cover underlying-share sourcing, tokenization infrastructure and possible distribution outside South Korea. They split the work between a Dinari proof of concept using its dShares model and an initial Ondo focus on the custody and operational framework for shares that could later be tokenized.
The Dinari proof of concept is intended to test an extension of dShares to Korean-listed equities. The model is designed to preserve applicable shareholder rights, including dividends and voting, while using locally listed Korean shares as the underlying assets rather than tokens that merely track share prices.
That distinction matters for investors assessing what a token would represent. A price-tracking token may follow an equity’s market value without being backed by the locally listed share itself; the proposed Dinari structure instead contemplates Korean shares as the underlying assets. The source does not provide further terms for how rights would be exercised or administered in a live product.
Dinari offers 724 tokenized U.S. stocks and exchange-traded funds through dShares, according to the reported partnership details. But the Korean proof of concept has not selected any specific companies, and Dinari CEO Gabe Otte said there is no public timeline for commercial availability.
Ondo’s agreement starts from a different operational question: how to source and custody Korean-listed shares that could later be tokenized. Kakaopay would operate a foreign-investor omnibus account to hold and administer the underlying shares, while the companies research token issuance and redemption. The structure would need to connect the offchain securities and their administration with any eventual onchain tokens.
Token issuance and redemption are part of the proposed arrangement, with Ondo and Kakaopay set to research both areas. The announcement does not specify the mechanics of any issuance or redemption process or when such a service might become available. Ondo’s involvement is therefore focused on work toward a framework, rather than a confirmed stock-token launch; its role sits within the wider tokenized-stock infrastructure discussion.
Otte told Cointelegraph that he sees institutional interest in South Korea around tokenization infrastructure that could connect Korean capital markets with global investors. He said the opportunity extends beyond creating tokenized versions of Korean equities to building infrastructure that could expand international distribution while preserving the rights and protections of the underlying securities.
Tokenized stocks remain concentrated in U.S. markets
The proposed Korean-equity work enters a tokenized-stock market that has grown but remains geographically narrow. RWA.xyz data cited in the report puts distributed value at about $3.2 billion as of late September 2026, with activity still heavily concentrated in tokenized versions of U.S. equities and ETFs.
The U.S. names cited include Strategy, Circle, Nvidia and Tesla, alongside major U.S. stock ETFs. Dinari’s existing dShares offering, with 724 tokenized U.S. stocks and ETFs, also illustrates the scale of the U.S.-focused catalogue described in the report. The proposed Korean work would test whether locally listed shares can be incorporated into a cross-border tokenization structure; it has not yet added Korean stocks to the market’s distributed value.
For investors, the potential significance is less about a confirmed new product than about whether tokenized securities can extend beyond familiar U.S. names while maintaining a connection to the underlying shares and their associated rights. That outcome depends on legal design, custody and investor access, not simply on creating a blockchain representation of an equity.
The current market figure should also be read as a measure of distributed value, not proof of broad adoption or liquidity across every tokenized stock. The primary report does not provide trading volumes, spreads or investor counts for the segment, and its snapshot cannot establish whether a future Korean offering would attract meaningful demand.
Regulatory framework and next steps remain decisive
South Korea is preparing a regulatory framework that could shape whether the proposed structure can proceed. The National Assembly approved amendments in January recognizing distributed ledgers as valid securities registries and permitting the issuance and circulation of token securities. The framework is scheduled to take effect in February 2027.
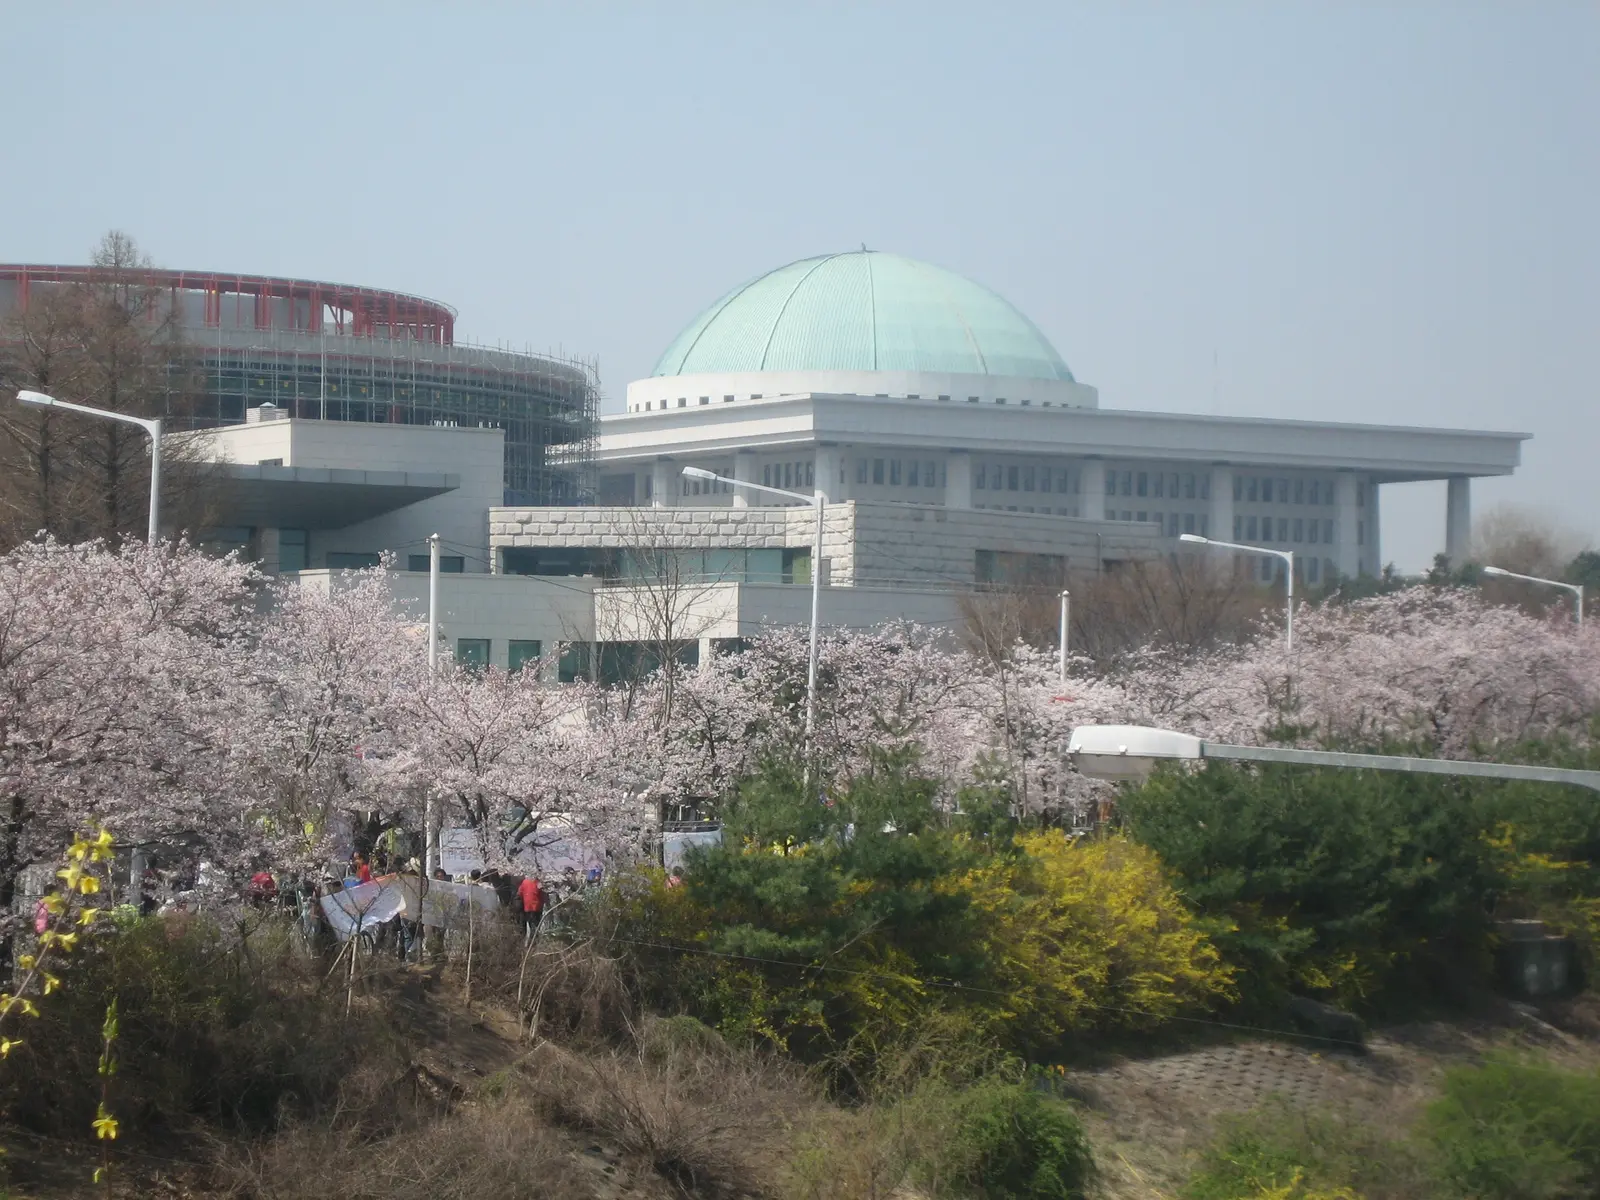
In June, the Financial Services Commission linked token-securities infrastructure to a broader overhaul of the country’s capital markets. The Korea Securities Depository is also developing infrastructure to connect its existing securities-account system with blockchain-based data. Those developments provide the institutional context for the partnerships, but they do not by themselves establish approval for a particular tokenized-equity product.
The broader South Korean tokenized-securities framework will be relevant to the project’s path, alongside rules in the overseas markets where any tokens might be distributed. The companies said a decision on whether or when to commercialize tokenized Korean equities will depend on those legal and regulatory requirements.
The near-term picture remains limited. No Korean-listed companies have been named for the Dinari proof of concept, there is no public commercialization timeline, and the Ondo work is still focused on researching share sourcing and custody alongside issuance and redemption. Those are meaningful design questions, but the announcement does not confirm a live pilot, launch date or investor-access terms.
For now, the agreements signal an effort to test how locally listed Korean shares could support onchain distribution without reducing the securities to price-only tokens. The key milestones are still conditional: a defined set of underlying shares, a workable custody and rights structure, and clearance across relevant jurisdictions. Until those pieces are established, the initiative remains a feasibility and infrastructure exercise rather than a new route to trade Korean stocks.
Follow CoinNews on X and Telegram for ongoing digital-asset market updates.
About Author

About Author